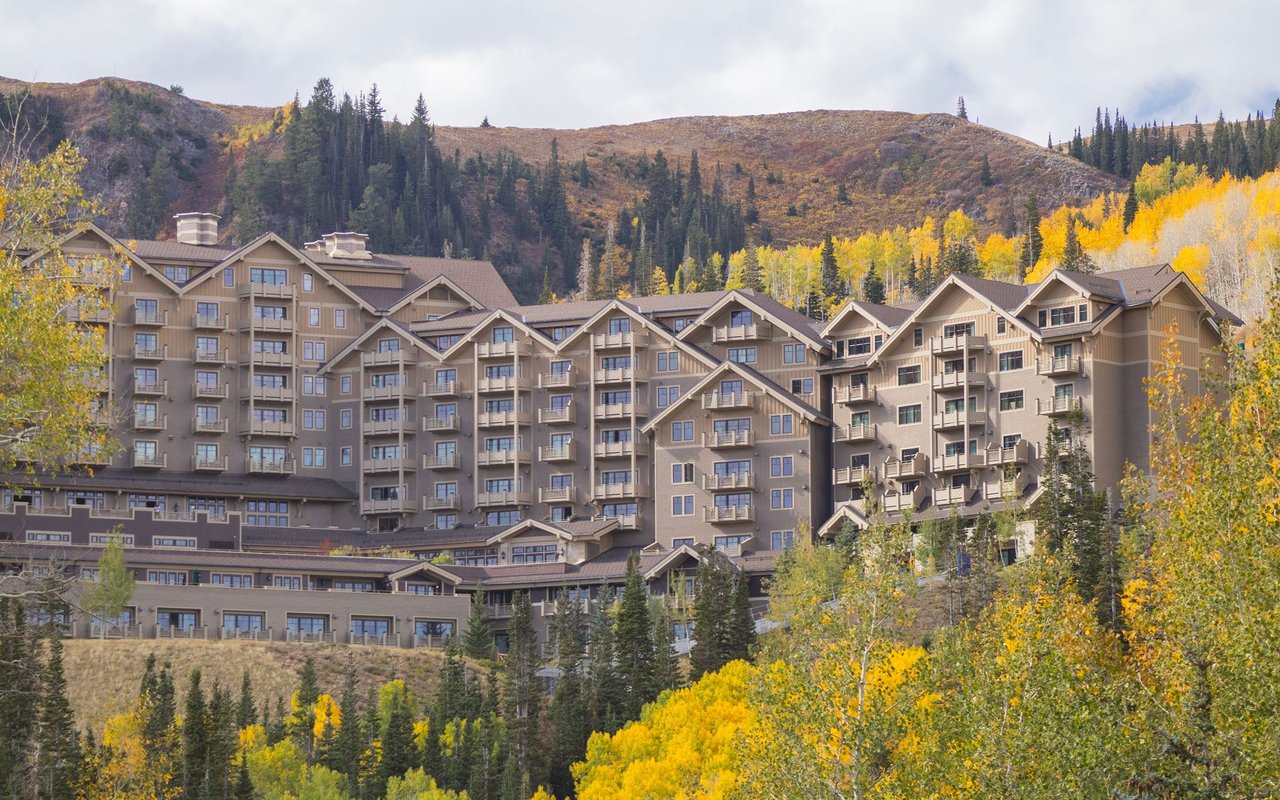
The $2,000 monthly HOA fee looked steep but manageable. Then six months after closing, the $47,000 special assessment letter arrived, new building envelope, elevator modernization, and parking structure waterproofing all hitting simultaneously.
HOA fees in Park City range from $200 monthly for simple townhome communities to $4,000+ for ultra-luxury resort condos. The monthly number gets negotiated into offers and factored into budgets. The hidden costs, special assessments, fee escalation, inadequate reserves, and expensive services that don't transfer, catch buyers after they own the property and can't easily exit.
Understanding what HOA fees actually cover, how to evaluate reserve fund health, when special assessments strike, and which luxury buildings justify premium fees prevents expensive surprises and aligns property selection with realistic long-term costs.
What HOA Fees Actually Cover (And What They Don't)
Park City condo buyers assume HOA fees cover "everything building-related." Reality is more nuanced, coverage varies dramatically between buildings, and gaps create unexpected owner expenses.
Common Inclusions in Most Park City HOA Fees:
- Exterior building maintenance: Roof, siding, paint, windows on building exterior.
- Snow removal: Snow removal from common areas, parking lots, driveways, and walkways.
- Landscaping and grounds maintenance: Landscaping and grounds maintenance.
- Common area utilities: Hallway lights, elevator power, pool heating.
- Building insurance: Structure and common areas, not individual unit contents.
- Management company fees: Management company fees.
- Reserve fund contributions: Reserve fund contributions.
- Trash removal: Trash removal from common dumpsters.
Common Inclusions in Luxury Resort Condos:
Everything above plus:
- 24/7 front desk and concierge services: 24/7 front desk and concierge services.
- Housekeeping: Housekeeping for common areas.
- Ski storage and boot warming: Ski storage and boot warming.
- Owner lounges and business centers: Owner lounges and business centers.
- Fitness centers and spa facilities: Fitness centers and spa facilities with towel service.
- Multiple pools and hot tubs: Multiple pools and hot tubs with attendants.
- Shuttle service: Shuttle service to ski resorts and Main Street.
- Valet parking services: Valet parking services.
- Property management coordination: Coordination for rentals.
- On-site maintenance staff: On-site maintenance staff.
What HOA fees typically DON'T cover:
- Unit interior maintenance: Appliances, fixtures, flooring, interior paint, plumbing fixtures.
- Utilities billed directly to units: Electricity, gas, water/sewer in some buildings.
- Individual unit insurance: HO-6 condo policy required.
- Parking space heaters or private garage features: Parking space heaters or private garage features.
- Special assessments: Special assessments for major capital projects.
- Furniture and furnishings for rental programs: Unless a specific capital fund exists.
- Renovations or upgrades: Renovations or upgrades to individual units.
- Damage to unit interiors from building issues: Water leaks and other damage until insurance processes.
The "Bare Walls in" vs "All In" Distinction:
Some HOA master insurance policies cover only structure to bare studs ("bare walls in"), owners insure everything from studs inward including drywall, flooring, fixtures, cabinets. Other policies are "all in" covering more interior finishes. This dramatically affects individual unit insurance needs and costs.
Ask specifically: Does master policy cover interior drywall, flooring, cabinets, countertops, or only structural framing? What is the master policy deductible, and who pays it when claims involve individual units? Most master deductibles run $10,000-$50,000+, if a building issue damages your unit, you may owe the deductible even though the problem wasn't your fault.
Common Surprise Expenses Owners Discover:
- Unit appliance replacements: $8,000-$15,000 for high-end refrigerator, dishwasher, washer/dryer sets in luxury units.
- Interior repainting: Every 5-7 years ($3,000-$8,000).
- Flooring replacement: From normal wear ($15,000-$40,000 for 1,500-2,500 sq ft units with quality materials).
- HVAC units serving individual condos: $5,000-$12,000 replacements.
- Plumbing repairs within unit boundaries: Owners typically responsible for pipes/fixtures inside unit.
- Window treatments and blinds: Not covered by HOA in most buildings, $5,000-$15,000 for quality treatments in luxury units.
The monthly HOA fee covers collective expenses. Individual unit maintenance remains owner responsibility regardless of fee amount.
Reserve Fund Health: The Most Important Due Diligence
Healthy reserve funds prevent special assessments. Underfunded reserves guarantee them. Most buyers never examine reserve fund adequacy until after special assessment letters arrive.
What Reserve Funds Should Cover:
- Roof replacement: 15-25 year lifespan, $500,000-$2M+ for large luxury buildings.
- Exterior painting: $200,000-$800,000 every 7-10 years.
- Parking structure repairs and resurfacing: $300,000-$1M every 10-15 years.
- Elevator modernization: $150,000-$400,000 per elevator every 20-25 years.
- HVAC system replacements for common areas: $200,000-$600,000 every 15-20 years.
- Pool equipment and resurfacing: $100,000-$300,000 every 10-15 years.
- Building envelope repairs: Windows, doors, waterproofing, $500,000-$3M+ depending on scope.
Reserve Studies Predict These Costs:
Professional reserve studies (updated every 3-5 years) inventory all major building components, estimate remaining useful life, project replacement costs, and calculate required annual reserve contributions. Well-managed HOAs follow reserve study recommendations, contributing adequate amounts annually so funds exist when projects hit.
Warning Signs of Inadequate Reserves:
- Low reserve fund balance: Reserve fund balance represents less than 50% of recommended funding level from reserve study.
- Outdated reserve study: HOA hasn't updated reserve study in 5+ years, costs and timelines become outdated, creating false security.
- Deferred maintenance: Visible throughout property, including patched roofs, peeling paint, cracked parking surfaces, outdated elevators.
- Recent history of special assessments: Signals chronic underfunding or poor planning.
- Low monthly reserve contributions: Relative to building age and condition, $100-200/unit monthly in older buildings signals problems.
How to Evaluate Reserves During Due Diligence:
Request last 2-3 years of HOA financial statements showing reserve fund balance and annual contributions. Review most recent reserve study (should be dated within last 3-5 years), compare current fund balance to study's recommended funding level. Calculate percentage funded: (Current reserves / Fully funded amount) x 100. Anything below 70% creates special assessment risk; below 50% virtually guarantees assessments. Review meeting minutes for last 12-24 months, look for discussions of deferred maintenance, needed projects, or debates about raising reserve contributions.
Real Park City examples:
- Older Deer Valley condo building: A $2M reserve balance sounds strong until the reserve study shows they need $5M for upcoming roof, elevator, and exterior work. They're 40% funded, special assessments coming.
- Newer Canyons Village building: With $800K reserves and a reserve study showing 90% funding, they're in excellent shape, special assessments unlikely for 10+ years.
- 1980s Prospector building: With $400K reserves, no reserve study since 2015, and visible deferred maintenance throughout, a special assessment is imminent, possibly $30,000-$80,000 per unit depending on project scope.
Lenders Care About Reserves Too:
Mortgage lenders review HOA financial statements before approving loans. Buildings with reserve funding below 10% of annual budget may be deemed "not warrantable," making conventional financing difficult or impossible. FHA loans require minimum reserve funding levels. Buyers planning to finance should verify the building qualifies for desired loan programs before committing.
Special Assessments: When, Why, and How Much
Special assessments represent the most painful HOA surprise, large, unexpected bills requiring immediate payment or payment plans with interest.
Common Triggers for Park City Special Assessments:
- Building envelope failures: Water infiltration through windows, roofs, or walls, $1M-$5M+ repairs.
- Elevator failures or code compliance issues: $150,000-$400,000 per elevator.
- Parking structure waterproofing and concrete repairs: $500,000-$2M+.
- Roof replacements: When reserves are insufficient, $500,000-$2M+ depending on building size.
- Plumbing system failures: Re-piping an entire building, $800,000-$3M.
- Fire suppression system upgrades: $300,000-$1M.
- ADA compliance upgrades: $200,000-$800,000.
- Storm damage not fully covered by insurance: Deductibles and uncovered items.
Assessment Amounts Vary by Unit Size:
HOAs allocate assessments based on ownership percentages (typically correlating to unit size). Small 1BR unit might owe $15,000-$25,000 for major project while large 3BR penthouse owes $60,000-$100,000+ for the same building-wide work. Seems unfair but reflects the larger unit's greater share of common expenses and building use.
Recent Park City Assessment Examples:
- Old Town luxury condo building: $2.1M building envelope repair, $35,000-$75,000 per unit depending on size.
- Empire Pass development: $1.8M parking structure waterproofing, $28,000-$52,000 per unit.
- Canyons Village building: $450,000 elevator modernization, $12,000-$18,000 per unit.
- Prospector complex: $850,000 roof replacement plus exterior paint, $22,000-$38,000 per unit.
Payment Terms and Consequences:
- Payment plans: HOAs typically offer payment plans (12-36 months) with interest (5-8% typical).
- Lump sum payments: Some require lump sum payment within 30-90 days.
- Failure to pay: Creates liens on properties, HOAs can eventually foreclose for non-payment though this is rare.
- Disclosure when selling: Special assessments must be disclosed to buyers when selling, unpaid assessments reduce sale proceeds or must be paid at closing.
Insurance Doesn't Always Prevent Assessments:
Building insurance carries high deductibles ($25,000-$100,000+). Damage below deductible gets paid by HOA (potentially triggering assessment if reserves are inadequate). Some damage types aren't covered (gradual deterioration, poor construction, code upgrades). Insurance covers sudden/accidental damage but not deferred maintenance consequences.
Can You Challenge Special Assessments?
Rarely successfully. HOA governing documents (CC&Rs) outline assessment authority. Most require board approval (sometimes owner vote for amounts exceeding certain thresholds). Unless HOA violated its own governing documents or acted outside legal authority, courts typically uphold properly enacted assessments. Your remedy is participating in HOA governance, voting for board members who plan responsibly, and lobbying for adequate reserve contributions to prevent assessments.
Fee Escalation: The 3-7% Annual Reality
Buyers budget based on current HOA fees without factoring inevitable increases. Over 10-30 year ownership periods, fee escalation dramatically impacts total cost.
Why Fees Increase Annually:
- Insurance costs: Rise 5-15% annually for mountain resort properties due to wildfire risk and replacement cost inflation.
- Labor costs: Increase with minimum wage and market rates for front desk, housekeeping, and maintenance staff.
- Utility costs: Rise faster than general inflation for electricity, natural gas, and water/sewer.
- Property management fees: Increase 3-5% annually.
- Deferred maintenance catch-up: Requires higher reserve contributions.
- Added services or amenities: Requested by owners.
Typical Escalation Rates by Building Type:
- Simple townhome communities: 2-3% annually (minimal services, mostly pass-through cost increases).
- Mid-range condo buildings: 3-5% annually (basic amenities, moderate management).
- Luxury resort condos: 4-7% annually (extensive services, high operating costs, staff-intensive amenities).
- Aging buildings: 5-10% annually (catch-up maintenance, rising repair costs, insurance increases).
10-year Projection Examples:
- $500/month starting fee: With 4% annual increases, Year 1: $500, Year 5: $608, Year 10: $740 ($240/month or $2,880/year increase).
- $2,000/month starting fee: With 5% annual increases, Year 1: $2,000, Year 5: $2,553, Year 10: $3,258 ($1,258/month or $15,096/year increase).
- $3,500/month starting fee: With 6% annual increases, Year 1: $3,500, Year 5: $4,683, Year 10: $6,270 ($2,770/month or $33,240/year increase).
30-year Projections Show Even More Dramatic Impact:
- $2,000/month at 5% annual growth: Reaches $8,644/month after 30 years.
- $3,500/month at 6% annual growth: Reaches $20,070/month after 30 years.
These aren't hypothetical, they're mathematical certainty based on historical cost growth patterns in ski resort communities.
Developer-subsidized Fees Create False Expectations:
New developments often have artificially low initial fees because developers subsidize operations to make units attractive. After developer turns control to owners (typically when 75-90% of units sell), fees jump 15-30% as true costs become apparent. Buyers in new developments should budget for immediate fee increases post-turnover plus ongoing escalation.
Budgeting for Fee Growth:
When evaluating affordability, use fee amount projected 5-10 years forward, not current amount. If $2,500/month feels like maximum affordable HOA fee today, look at properties currently charging $1,800-2,000/month, they'll grow into your limit. Properties currently at your limit will exceed it within 3-5 years. This conservative approach prevents payment stress as fees rise.
Luxury Buildings: When $4,000/Month Makes Sense
Some Park City condos charge $3,000-$4,000+ monthly HOA fees. Buyers question whether luxury services justify these costs or if they're paying for features they don't use.
What Justifies Premium HOA Fees:
- 24/7 concierge and front desk: Creating a hotel-like experience.
- Full-service property management: Handling all owner needs including rental coordination.
- Housekeeping services: For common areas and sometimes unit turnover.
- Multiple pools, hot tubs, fitness centers, and spa facilities: With trainer services and other amenities.
- Ski valet services: Equipment storage, boot warming, slope-side access.
- Shuttle services: To slopes and town.
- Valet parking: In buildings where parking is constrained.
- On-site maintenance staff: Providing quick response to owner needs.
- Owner lounges, business centers, meeting rooms, and private dining facilities: Offering additional shared amenities.
Cost Analysis for $3,500/Month Luxury Building:
- 24/7 staffing: Front desk, concierge, housekeeping, approximately $1,200/month per unit when costs are spread across all owners.
- Utilities for extensive amenities: Pool heating, spa operations, shuttle fuel, approximately $400/month per unit.
- Building insurance: On luxury property with high replacement costs, approximately $300/month per unit.
- Property management fees: For full-service coordination, approximately $250/month per unit.
- Reserve contributions: For high-end finishes and systems, approximately $600/month per unit.
- Common area maintenance and snow removal: Approximately $400/month per unit.
- Miscellaneous expenses: Administrative costs, supplies, landscaping, and legal expenses, approximately $350/month per unit.
- Total: $3,500/month, every dollar goes to actual services or necessary reserves.
When Luxury Fees Make Sense:
- Properties generating significant rental income: Management services and amenities attract premium nightly rates.
- Second home owners visiting occasionally: They want everything handled seamlessly.
- Buyers who use amenities regularly: Fitness center, pools, spa, and concierge.
- Properties with expensive equivalent services: These services would cost $3,000-4,000/month if purchased separately.
- Owners who value hassle-free ownership: They prioritize convenience over cost optimization.
When Luxury Fees Don't Make Sense:
- Full-time residents who don't use resort services: They use a fitness center in town, don't need concierge services, and drive their own car.
- Properties not generating rental income: No rental income to offset costs.
- Buyers on tight budgets: $3,500-4,000/month creates financial stress.
- Owners who prefer managing properties directly: They don't want to pay for services they don't need.
- Properties with simpler alternatives: Simpler buildings in the same location offer similar unit quality at half the HOA cost.
Comparing Luxury vs Standard Buildings:
- Luxury Deer Valley condo: $3,800/month HOA, ski-in/ski-out, full services, generates $120,000 annual rental income (gross). Net cost after rental income and expenses: roughly break-even to slight positive.
- Standard Deer Valley condo: $1,400/month HOA, ski-in/ski-out, basic services, generates $80,000 annual rental income (gross). Net cost after rental income and expenses: positive cash flow of $15,000-25,000 annually.
Decision depends on priorities: do you value luxury services and hotel-like experience, or maximize cash flow with basic services?
Ski Resort-Managed vs Independent HOAs
Park City condos operate under different management models affecting costs, services, and owner autonomy.
Ski Resort-managed Properties:
- Resort management: Buildings at base areas often managed by resort companies (Deer Valley Company, Vail Resorts for Canyons).
- Higher fees: Owners pay more but access resort services, marketing, and rental pools.
- Integrated services: The resort handles everything, including maintenance, rentals, housekeeping, and front desk services.
- Less owner control: The resort sets fees, standards, and policies.
- Rental income structure: Rental income is channeled through resort programs (typically 30-40% commission to resort).
- Resort branding: Properties market as resort-branded, potentially commanding premium nightly rates.
Independent HOA-managed Properties:
- Independent management: Owners hire independent management companies or self-manage.
- Lower fees: Less overhead and negotiated vendor contracts reduce costs.
- More owner control: Owners have more control over budgets, services, and vendors.
- Optional rental programs: Owners can self-manage rentals or use any property manager.
- More flexibility: Owners have more flexibility but need greater involvement and decision-making.
Cost Comparison Examples:
- Resort-managed Deer Valley condo: $3,200/month HOA including resort services, rental program access, and branded marketing.
- Independent Deer Valley condo: $1,800/month HOA for similar services through independent providers, with owners arranging their own rental management.
The $1,400/month difference ($16,800 annually) pays for resort brand association, integrated services, and simplified ownership. Whether it's worth the premium depends on rental income goals and personal preference for integrated vs à la carte services.
Rental Income Implications:
Resort-managed properties tap into resort reservation systems and marketing, potentially generating more bookings. However, resort commissions (30-40%) plus HOA fees consume substantial rental income. Independent properties have lower HOA costs but require separate rental management (20-30% commissions) and marketing efforts. Net income often similar, but cash flow patterns differ.
Transition Risks:
Some buildings start resort-managed and later transition to independent management as owners seek cost control. Transitions create disruption, service gaps, contract renegotiations, staff changes. Buyers should understand management model stability and any transition plans affecting future operations.
Due Diligence Checklist: What to Request
Thorough HOA due diligence prevents expensive surprises. Standard purchase contracts allow 10-15 days for HOA review, use this time efficiently.
Essential Documents to Request:
- Last 24 months of HOA meeting minutes: Look for discussions of deferred maintenance, upcoming projects, financial challenges, and owner disputes.
- Last 3 years of audited financial statements: Showing income, expenses, and reserve fund balances.
- Current operating budget: Broken down by category.
- Most recent reserve study: Ideally within the last 3 years, with funding recommendations.
- HOA governing documents: Declaration of CC&Rs, Articles of Incorporation, Bylaws, Rules & Regulations.
- Master insurance policy: Showing coverage limits, deductibles, and what's covered.
- List of current and planned special assessments: Current and planned special assessments.
- Status letter (estoppel certificate): Confirming dues are current, there are no violations, and listing transfer fees.
- Management agreement: Showing management company, services provided, and fees.
- Vendor contracts: For major services such as snow removal, landscaping, and janitorial work.
Questions to Ask Hoa Board or Management:
- Reserve funding: What is the reserve fund percentage funded according to the last reserve study?
- Past special assessments: Have there been special assessments in the last 5 years? What were they for and how much?
- Planned special assessments: Are any special assessments planned or under discussion?
- Reserve study timing: When was the last reserve study completed? Is an update scheduled?
- Upcoming replacements: What major building systems or components will need replacement in the next 5-10 years?
- Insurance costs: How is the HOA handling rising insurance costs? Are there any coverage gaps or concerns?
- Dues delinquencies: What percentage of owners are current on dues? Are there any significant delinquencies?
- Pending litigation: Are there any pending or threatened lawsuits involving the HOA or building?
- Owner turnover rate: What is the owner turnover rate? High turnover can signal problems.
Red Flags Requiring Extra Scrutiny:
- Low reserve funding: Reserve funding below 50% of the recommended level.
- Recent special assessments: Special assessments levied in the last 2-3 years.
- Visible deferred maintenance: Aging roof, peeling paint, and cracked parking surfaces.
- Contentious meeting minutes: Meeting minutes showing contentious disputes or financial concerns.
- Rising delinquency rates: Rising delinquency rates on HOA dues.
- Pending litigation: Especially related to construction defects or building envelope issues.
- Insurance problems: Recent insurance non-renewals or dramatic premium increases.
- High owner turnover: Suggesting dissatisfaction.
- Management company changes: Changes in the last 1-2 years.
- Developer control: Developer still controlling the HOA board 5+ years after construction completion.
Deal-breaker Scenarios:
- Critically underfunded reserves: Reserve fund below 30% with major projects imminent.
- Unpaid special assessment: Special assessment already levied but not yet paid by seller, meaning you inherit liability.
- Ongoing construction defect litigation: With unclear resolution timeline and costs.
- Financing restrictions: Building deemed not warrantable for conventional financing.
- Chronic operational dysfunction: Failed votes, management turnover, and owner conflicts.
Hidden Costs Beyond Monthly Fees
HOA fees get the attention, but other condo ownership costs surprise buyers.
Transfer Fees at Purchase:
- HOA transfer fees: Many HOAs charge $500-$2,000 when ownership changes.
- Capital contribution fees: Some luxury developments charge 1-2% of purchase price ($20,000-$100,000 on $2M-5M condos).
- Private club or resort dues: Required as a condition of ownership ($5,000-$20,000 annually).
- Document review fees: Charged by management companies ($200-$500).
Rental Program Requirements:
- Furniture packages: Some HOAs with rental programs require an initial outlay of $50,000-$150,000.
- Annual furniture replacement reserves: $3,000-$8,000 per year for wear items.
- Mandatory property management participation: Owners can't opt out or use different managers.
- Occupancy restrictions: Limits on owner use during peak rental periods.
Resort Amenity Fees:
- Separate amenity fees: Properties in resort villages may require separate fees for parking, pool/fitness center access, or club memberships, not included in HOA fees.
- Ski storage lockers: $500-$2,000 annually beyond HOA fees in some buildings.
- Guest parking fees: $10-$30 per day for visitor vehicles.
Renovation Restrictions and Costs:
- Architectural review fees: HOAs often require architectural review of unit renovations ($500-$2,000 fees).
- Contractor insurance requirements: Mandated requirements increase project costs.
- Elevator reservation fees: For moving furniture/materials ($200-$500).
- Restricted work hours: No evenings/weekends, extending project timelines and costs.
- Required HOA-approved contractors: Limits competitive bidding.
Special Requirements for Owners:
- Vacation rental licensing fees: If allowed, $300-$800 annually.
- Mandatory property management agreements: Required in some buildings.
- HOA meeting attendance or proxy requirements: Required in some buildings.
- Fines for rule violations: $50-$500 per occurrence for parking, noise, pet violations, etc.
Factor these costs into total ownership budgets. A $2,500/month HOA fee building might actually cost $3,200/month when all extras are included.